Mortgage Loan Details
Adjust any value for instant results
Mortgage Payment Calculator with PMI and Taxes
Credit information is one factor lenders may consider when pricing a mortgage. Review your reports for accuracy and compare actual Loan Estimates; no credit-monitoring product guarantees a rate reduction.
- 3-Bureau credit reports (TransUnion, Experian, Equifax)
- Score simulator to identify quick improvements
- Actionable credit report dispute tools
Protect your earnest money deposit and specify inspection terms before making an offer on a residential property.
- State-specific Real Estate Purchase Agreement
- Promissory Notes & Seller Financing contracts
- Attorney-reviewed, instant PDF download in minutes
Optimize Your Mortgage Interest Rate Before Applying
Mortgage pricing can consider credit scores along with loan-to-value, loan type, occupancy, property, debt-to-income, and other factors. Improving a credit profile may help, but no specific point increase guarantees a lower rate or a particular savings amount:
Tools to review credit information and monitor changes. Outcomes vary by individual credit file and scoring model.
Side-by-side comparison of your Equifax, Experian, and TransUnion files—the exact 3 bureaus mortgage underwriters pull.
Simulate paying off credit card balances or increasing credit limits to see how your score and monthly mortgage payment respond.
Making an Offer or Structuring a Private Loan?
Protect your earnest deposit and lock in terms legally before closing. Create custom, state-compliant real estate contracts in under 5 minutes with our verified partner LawDepot:
Legally binding contract specifying purchase price, earnest deposit, financing contingencies, and closing date.
Enforceable promise to repay a loan with interest rates, amortization schedule, and late fee clauses.
Owner-financing contract where seller retains title until buyer completes all monthly installment payments.
Credit Score Boost & 3-Bureau Reports
Partner: SmartCredit ($1 Trial)How much annual household income do you realistically need to afford this mortgage without becoming financially stressed?
See how adding extra principal payments slashes total interest over time and accelerates your debt-free date compared to your original term.
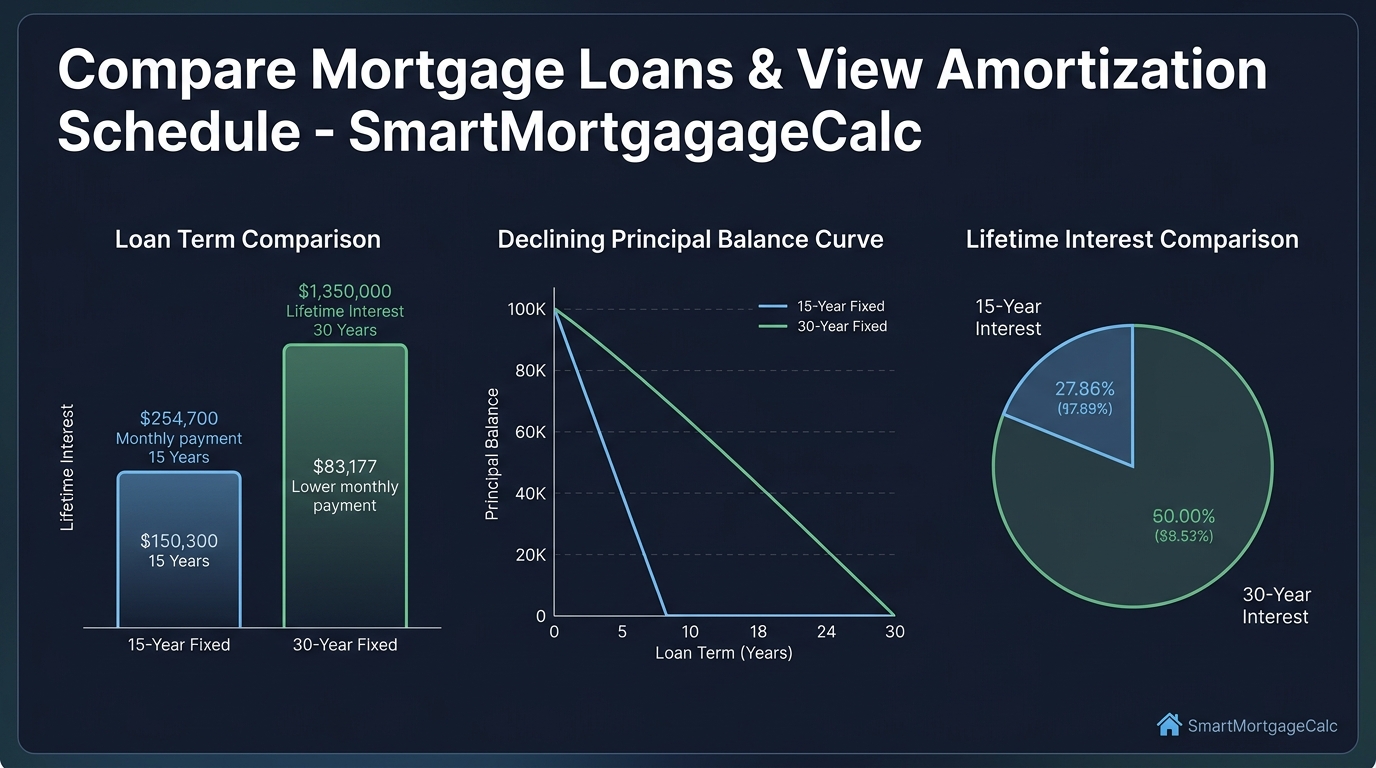
Debating between a 15-year vs. 30-year term, or comparing two lender interest rate quotes? Test scenarios side-by-side with interactive payment and balance curves.
Amortization Schedule
See how each payment chips away at your principal loan balance.
| Year | Principal Paid | Interest Paid | Total Paid | Ending Balance |
|---|
How Extra Payments Toward Principal Save $100,000+ in Interest
Mathematical MilestoneFor illustration, on a $350,000 loan at a 6.75% fixed rate over 30 years, total scheduled interest is $467,234. Applying an additional $250/month toward principal lowers total interest to $332,762 — saving $134,472 in direct interest and eliminating 7.4 years (89 monthly payments) from your amortization term.
AI Mortgage Scenario Assistant
Select popular questions home buyers Quick Reference Answers to receive instant deterministic calculations, 2026 underwriting formulas, and compliance rules.
For illustration, assume a 6.75% 30-year fixed rate, property taxes at 1.1% of home value, and $100/month homeowners insurance. Actual qualification depends on the lender and the full borrower profile:
Mortgage Payment Rules & Illustrative Benchmarks
M = P × [r(1+r)ⁿ] / [(1+r)ⁿ - 1]. Calculates fixed monthly principal and interest with deterministic accuracy.
| Loan Term | Benchmark APR | Monthly P&I | Lifetime Interest | Interest Saved | Payoff Duration |
|---|---|---|---|---|---|
| 30-Year Fixed | 6.75% | $2,594 / mo | $533,981 | $0 (Baseline) | 360 Months (30.0 Yrs) |
| 15-Year Fixed | 5.95% | $3,365 / mo | $205,634 | Save $328,347 | 180 Months (15.0 Yrs) |
U.S. Homebuyer Learning Center
Go beyond the monthly payment. Explore practical guides to mortgage affordability, down payments, closing costs, credit scores, loan programs, refinancing, discount points, property taxes and insurance.