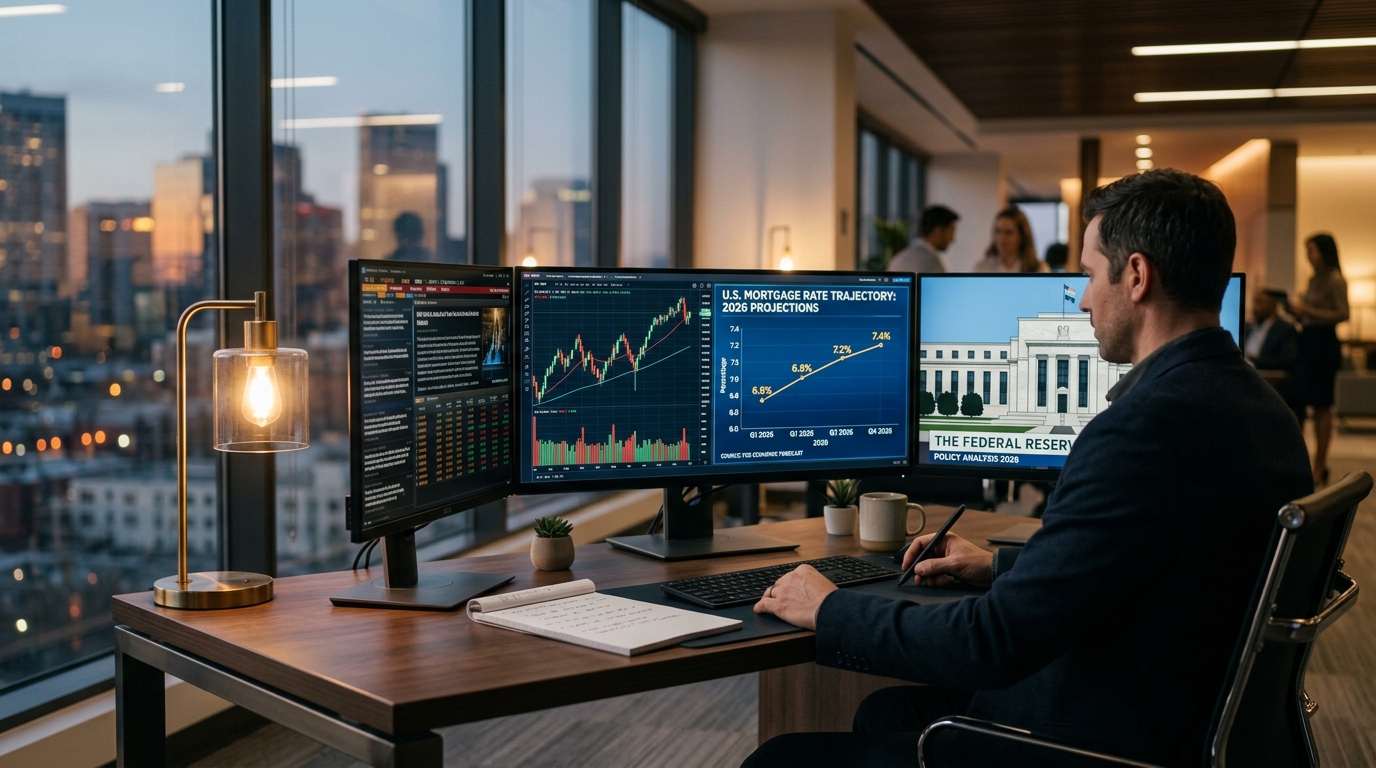
As we navigate the 2026 housing market, prospective homebuyers and existing homeowners contemplating a refinance are confronted with a transformed interest rate landscape. Following the unprecedented rate hikes of 2022–2023 and the subsequent disinflation cycle, the 30-year fixed mortgage rate has settled into a defined corridor between 6.15% and 6.85%.
Key Takeaway for 2026 Homebuyers
Mortgage rates do not directly mirror the Federal Reserve's Federal Funds Rate. Instead, they track the 10-Year U.S. Treasury Note yield plus an institutional mortgage spread (~240 to 280 basis points). Even modest drops in headline inflation can cause mortgage rates to decline ahead of official Fed rate adjustments.
1. The 10-Year Treasury Spread & What Moves Mortgage Rates
A widespread misconception among retail consumers is that the Federal Reserve directly sets mortgage rates. In reality, fixed-rate residential mortgages are securitized into Mortgage-Backed Securities (MBS) and purchased by institutional bond investors. The baseline anchor for pricing MBS is the 10-Year Treasury Yield.
Historically, the spread between the 10-Year Treasury and the 30-year fixed mortgage rate hovered around 170 basis points (1.70%). However, elevated volatility in long-duration bonds has kept this spread expanded around 250–270 bps. As secondary market volatility calms throughout 2026, compression of this spread alone can provide a 40–60 basis point tailwind to lower borrowing costs without requiring dramatic Fed easing.
🧮 Dynamic Fixed-Rate Mortgage Calculator with Live Benchmark Rates
Test how current Federal Reserve interest rate projections directly impact your monthly purchasing power and total borrowing costs.
Model Current Rate Scenarios2. Inflation Dynamics (CPI & Shelter Component)
The primary driver of bond yield direction remains the Consumer Price Index (CPI) and Personal Consumption Expenditures (PCE) price index. The largest and stickiest constituent of headline inflation has historically been "Shelter" (Owner's Equivalent Rent).
Because shelter metrics in official government statistics operate on an 11- to 15-month lag compared to private-market real-time rental indexes (such as Zillow and Apartment List), modern research indices confirm that underlying residential inflation has normalized faster than official headline figures. As these official shelter figures fully catch up, bond yields are forecast to drift steadily downward toward the 3.80%–4.10% range on the 10-Year Treasury.